The Sovereign AI Bank
Why Crédit Agricole's Mistral Partnership Signals a New Phase of Banking Transformation
20 October 2026 | Digital Pulse by Eastern Legacy | Digital News Decrypted
From AI experimentation to industrial capability
For much of the generative AI era, the central question for financial institutions has been how quickly they could introduce new tools into their organisations. Chatbots, knowledge assistants, coding copilots and document-processing applications became the most visible manifestations of AI adoption.
The announcement by Crédit Agricole of a strategic partnership with Mistral AI suggests that a different question is now emerging: how should a banking group organise, control and industrialise artificial intelligence as a shared strategic capability?
Through its newly created Crédit Agricole Artificial Intelligence entity, the group intends to pool technological assets, accelerate deployment and support AI transformation across its businesses. The partnership with Mistral extends beyond access to language models to include contributions to the development of a group-wide AI platform.
Alongside this initiative, Crédit Agricole is working with Prisme.AI to enable employees to create and orchestrate agents connected to enterprise information systems.
Taken together, these developments represent more than another technology procurement decision. They point towards the emergence of a new layer of banking infrastructure.
AI as a shared industrial utility
Large banking groups face a structural challenge when adopting artificial intelligence.
Individual business units may develop useful applications, but decentralised experimentation often leads to fragmented architectures, duplicated investment, inconsistent governance and limited reuse.
Why shared AI platform offers a different model
Instead of each department independently sourcing models, configuring security controls and building integrations, the institution can establish common capabilities that serve multiple business lines.
This architecture potentially generates economies of scale in inference, security, maintenance and development. It can also accelerate deployment by allowing teams to reuse approved components rather than repeatedly rebuilding them.
However, the benefits are not automatic.
Shared infrastructure requires substantial upfront investment, clear service ownership, internal pricing arrangements and the ability to accommodate heterogeneous business requirements. Centralisation can also concentrate operational risk.
The economic challenge is therefore to establish whether the benefits of reuse and standardisation exceed the costs of operating a complex group-wide platform.
Sovereignty moves from policy to architecture
The partnership also illustrates how digital sovereignty is evolving.
For European institutions, sovereignty is often discussed in terms of domestic technology champions, cloud localisation or reducing dependence on American hyperscalers.
These dimensions matter, but they do not fully capture the issue.
A genuinely sovereign AI architecture requires the ability to determine where data is processed, who can access it, how models are deployed, how systems are audited and whether critical services can continue when a provider becomes unavailable.
It also requires credible exit options.
A bank using European models may still depend on non-European chips, networking equipment, software components or cloud infrastructure. Conversely, a hybrid architecture incorporating international suppliers can preserve substantial institutional control when supported by appropriate technical and contractual safeguards.
Crédit Agricole's announced approach reflects this complexity. Its infrastructure strategy combines private cloud, European partners and complementary solutions according to workload sensitivity and criticality.
This suggests that the practical objective is not technological isolation, but greater strategic optionality. The distinction is fundamental: sovereignty should be measured by effective control over critical dependencies, not simply by the nationality of suppliers.
The orchestration layer may become a more important sovereignty asset than the language model itself.
Digital sovereignty should not be confused with technological nationalism.
The nationality of a technology supplier may influence jurisdictional exposure and geopolitical risk, but it does not, by itself, determine an institution's autonomy.
What matters is the degree of effective control over critical dependencies: the ability to govern data, operate essential systems, retain architectural flexibility, substitute suppliers and maintain continuity when external conditions deteriorate.
A European technology stack built around irreplaceable proprietary dependencies may offer less effective sovereignty than a diversified international architecture designed around portability, independent governance and operational resilience.
The strategic objective is therefore not technological self-sufficiency at any cost, but the ability to preserve institutional freedom of action despite technological interdependence.
In this sense, sovereignty is not defined by where technology comes from, but by how much control an institution retains when that technology becomes indispensable.
The partnership offers an interesting case because it combines several layers of the AI value chain.
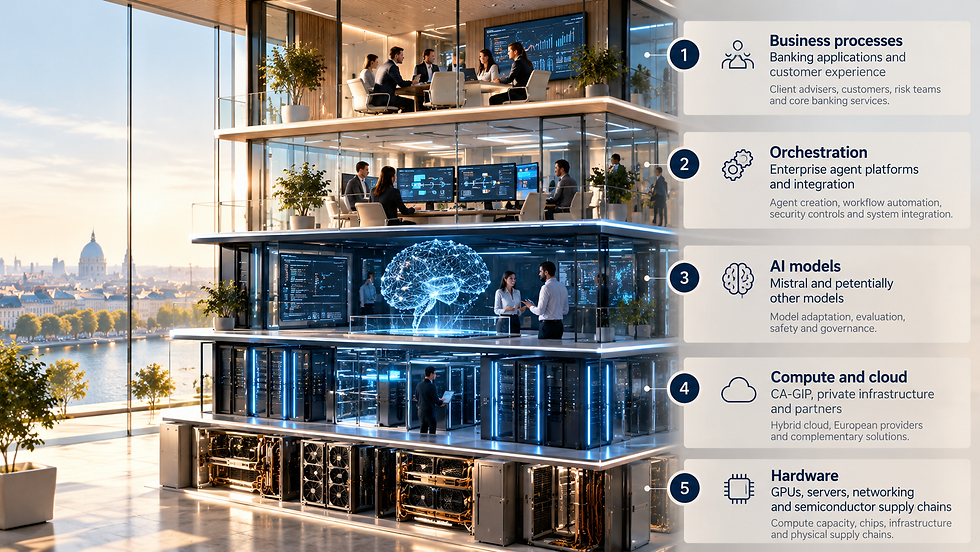
Even if Crédit Agricole uses European models and infrastructure providers, several questions remain essential. Can the bank migrate its applications to another model provider? Can it continue operating if Mistral changes its commercial terms? Can it deploy models independently of the provider? Does it control the agent orchestration layer and its interfaces? Can critical services survive the loss of a cloud region, hardware supplier or software dependency?
The answers would tell us considerably more about its effective sovereignty than the nationality of its partners. In particular, the orchestration layer may become a more important sovereignty asset than the language model itself.
Why? Because the orchestration layer increasingly determines which data is accessed, which business processes are executed, which models are called, and what controls govern AI-driven actions.
An institution that controls this layer may retain considerable freedom to substitute models underneath it. Conversely, one that outsources its orchestration architecture may become deeply dependent on a provider even when it retains ownership of its data.
How to measure sovereignty at the level of the Entreprise?
Digital sovereignty is not a binary condition, but a journey towards greater institutional autonomy. It evolves through three levels of maturity: from localisation, which provides geographic and legal safeguards, to operational control, and ultimately to resilience and strategic optionality. The true measure of sovereignty is not where technology originates, but an institution's ability to govern its critical dependencies, switch providers and maintain essential operations under disruption.

A bank claiming technological sovereignty should be able to demonstrate that it can maintain critical services and replace essential suppliers within an acceptable period, at an acceptable cost and without unacceptable data or operational risks.
This could be measured through concrete indicators as:
Time required to migrate a critical AI workload to another provider.
Percentage of critical applications dependent on proprietary interfaces.
Ability to operate models without continuous access to the original supplier.
Recovery time following loss of a major technology provider.
Concentration of critical workloads across suppliers and jurisdictions.
Cost of switching providers relative to the annual cost of the service.
These indicators are more operationally meaningful than a simple percentage of European technology procurement.
Digital sovereignty must be tested, not simply declared. Can a bank migrate a critical AI workload to another provider within 30 days? Can it continue operating if its cloud or AI supplier becomes unavailable? Does it retain control over its data, encryption keys and business processes? Can it replace a technology partner without prohibitive costs or major service disruption?
Ultimately, sovereignty is not measured by the nationality of technology providers, but by an institution's proven ability to maintain control and continuity when critical dependencies are challenged.
The agentic transformation of banking
The most consequential element of the announcement may be the ambition to transform core banking processes through AI agents.
Traditional enterprise AI primarily supports human activities. It retrieves documents, summarises information, generates content or helps employees make decisions.
Agentic systems introduce the possibility of coordinating sequences of actions across enterprise applications.
In banking, this could eventually reshape activities such as customer onboarding, compliance documentation, service operations, internal reporting and administrative workflows.
Yet moving from assistance to action fundamentally changes the risk profile.
An assistant that produces an incorrect summary creates one type of exposure. An agent authorised to interact with customer records, initiate workflows or trigger downstream operations creates another.
Successful industrialisation therefore requires more than accurate models. It demands carefully defined permissions, secure interfaces, transaction boundaries, monitoring, escalation procedures and human accountability. This is particularly important in a sector where operational resilience and third-party dependencies are already central supervisory concerns.
The European Central Bank's 2026 commentary on operational resilience highlights the growing importance of cyber risk, technology concentration and continuity as AI capabilities become more deeply embedded in financial services.
The strategic opportunity is significant, but so is the responsibility associated with deploying autonomous capabilities at scale.
The economics of the sovereign AI bank
The commercial sustainability of this model remains an open question.
European institutions must reconcile several objectives that do not always align naturally: technological autonomy, advanced performance, low operating costs, cybersecurity, regulatory compliance and rapid innovation.
A highly controlled infrastructure may offer governance advantages but require additional investment in engineering, operations and resilience.
Smaller, specialised models may reduce inference costs for certain tasks, but their suitability must be demonstrated through rigorous testing.
Similarly, agentic automation may create value by reducing manual work, yet integration and supervision costs can erode expected savings. This makes total cost of ownership a more meaningful metric than the price of model access alone.
Successful industrialisation requires more than accurate models. It demands carefully defined permissions, secure interfaces, transaction boundaries, monitoring, escalation procedures and human accountability.
Banks should evaluate AI through the economics of completed business processes, incorporating infrastructure expenditure, development, integration, operational controls, exception handling and realised outcomes.
The critical question is whether an AI-enabled workflow can deliver a reliable service at a lower risk-adjusted cost, or create sufficient additional customer value to justify its expense. Without that evidence, industrial-scale AI risks becoming industrial-scale technology spending.
A new competitive dynamic for European banking
The implications extend beyond Crédit Agricole.
Large institutions may increasingly seek to establish their own AI platforms, supported by strategic partnerships with model providers and infrastructure operators.
Smaller banks may face a different choice: invest in shared industry utilities, purchase managed AI services or depend more heavily on established banking technology vendors.
This could reshape competitive dynamics across the sector.
If AI platforms generate meaningful economies of scale, large groups may gain advantages in development speed, operational efficiency and access to specialised talent.
At the same time, independent software providers and European AI companies could benefit from demand for secure, interoperable and sector-specific technologies.
For Mistral, partnerships with major regulated institutions provide opportunities to demonstrate the performance and reliability of its technologies under demanding operational conditions.
For Europe, these relationships could help connect AI research and model development with sustained enterprise demand.
But regional industrial development should not be confused with guaranteed competitiveness. European providers will still need to demonstrate that they can deliver performance, reliability and economics that compare favourably with global alternatives.
What should banking leaders watch next?
The next stage of AI transformation should be judged against business and operational outcomes rather than announcements. For Crédit Agricole, the important indicators will include the proportion of processes meaningfully redesigned, the time required to deploy new AI capabilities, the cost of operating the shared platform and the degree of reuse across business units.
Equally important will be the robustness of governance: whether agents can be audited, whether critical functions can be recovered after disruption and whether technology dependencies remain manageable.
The strongest evidence of success would be a combination of measurable productivity improvements, better customer experiences and sustained operational resilience.
Conclusion: The next banking infrastructure race
Crédit Agricole's partnership with Mistral AI illustrates a broader transition in enterprise artificial intelligence. The market is moving beyond the question of who can access the most capable models towards who can integrate intelligence most effectively into complex institutions.
For banks, this means building capabilities that combine data, infrastructure, software, governance and organisational transformation. For Europe, it suggests that AI sovereignty will ultimately depend on whether regional technology ecosystems can support economically competitive, reliable and scalable enterprise solutions.
And for the wider financial sector, it raises a more fundamental question.
Could the next generation of banking infrastructure be defined not by the systems that record transactions, but by the intelligence layer that orchestrates how banking work gets done?
The answer will depend less on the sophistication of AI demonstrations than on the ability to translate technology into trusted, measurable and sustainable institutional capability.
Sources & Further Reading
Crédit Agricole — Industrial deployment of artificial intelligence (20 October 2026). Official announcement detailing the Mistral partnership, Prisme.AI collaboration and group-wide AI infrastructure strategy.
European Central Bank — Strengthening operational resilience for the age of AI (3 June 2026). Supervisory perspective on AI, cyber risk, technology dependencies and operational resilience.
CEA — Renewal of the CEA–Mistral partnership (22 June 2026). Another European institutional example of deploying sovereign AI capabilities under sensitive data and security constraints.
European Central Bank — Annual Report 2025 (2026). Institutional context on DORA, outsourcing and the supervisory importance of technology resilience.


Comments